Category: Refinance
Learn about mortgage refinancing options, costs, eligibility requirements, cash-out refinancing, rate reductions, and strategies for homeowners considering refinancing.
Refinancing a Mortgage in California: Costs, Options, and How It Works
Refinancing a mortgage in California means replacing your current home loan with a new one. The new loan may lower the interest rate, change the loan term, switch from an adjustable rate to a fixed rate, remove mortgage insurance in some cases, or allow you to take cash out from home equity. Because California home…
Read More
Refinance After Bankruptcy: Waiting Periods, Loan Options, and Qualification Factors
Refinancing after bankruptcy is possible, but timing rules, credit recovery, home equity, income stability, and the type of bankruptcy all play a major role. A refinance replaces your current mortgage with a new loan, and after a bankruptcy filing, lenders usually want to see that the bankruptcy has been discharged or dismissed, that enough time…
Read More
Cash-Out Refinance Closing Costs: What Fees to Expect and How Much You’ll Pay
Cash-out refinance closing costs are the fees and upfront expenses paid to replace your current mortgage with a larger new loan and receive the difference in cash. These costs matter because they reduce the net amount of money you actually receive, and they can change whether the refinance makes financial sense. Even if the new…
Read More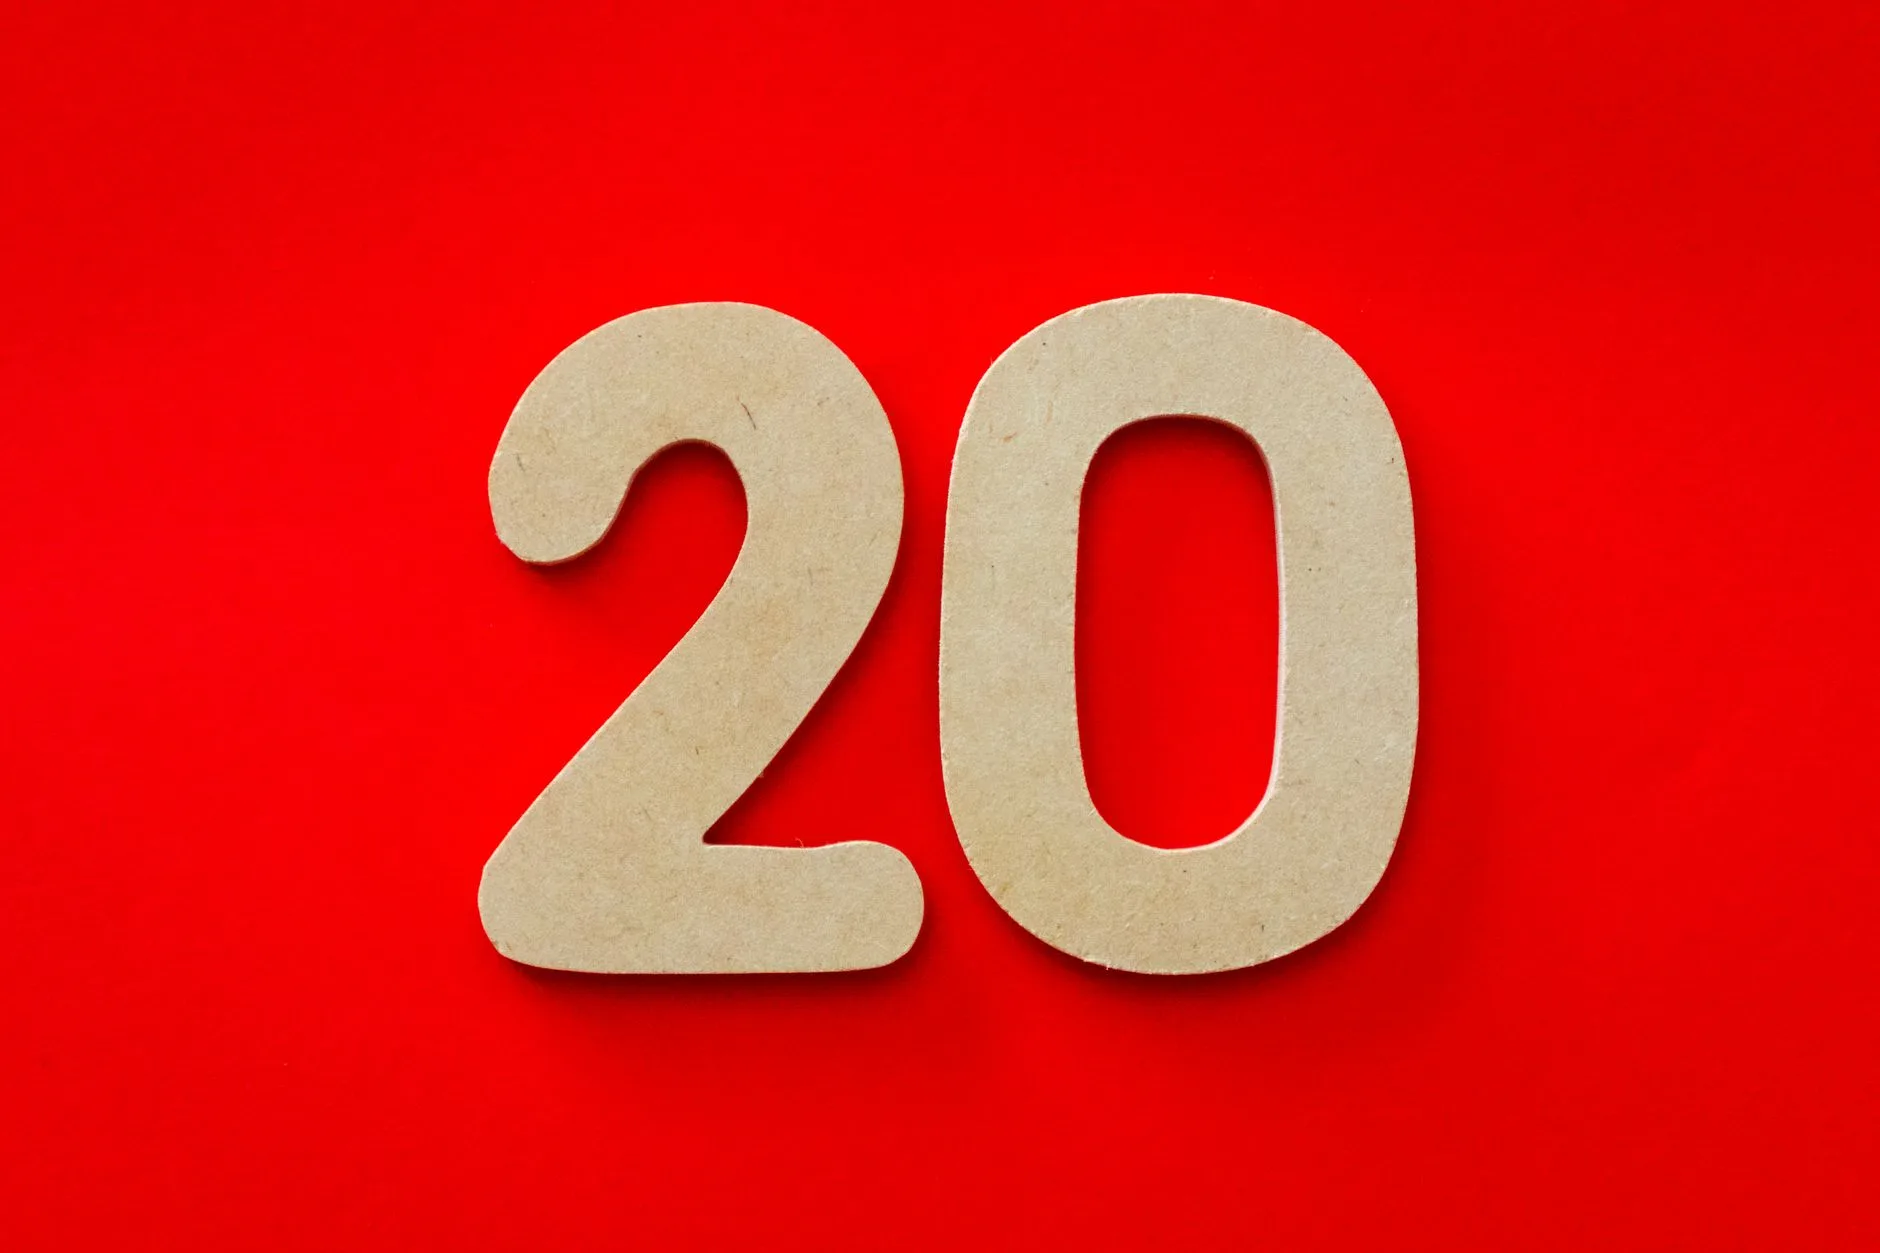
Refinancing Requirements With 20% Equity: What Lenders Look For
Refinancing requirements with 20% equity are often more favorable than requirements for homeowners with less equity, because a lower loan-to-value ratio can reduce lender risk. In plain English, 20% equity means you own one-fifth of your home’s value and owe the remaining portion on your mortgage. That amount of equity can help with approval, may…
Read More
Michigan Refinance Rates: How to Compare Costs, APR, and Loan Options
Refinance rates in Michigan are the interest rates lenders offer when a homeowner replaces an existing mortgage with a new one. Those rates matter because they affect your monthly payment, total interest cost, closing costs, and how long it may take for a refinance to pay for itself. A lower rate can reduce payment or…
Read More
Texas Refinance Rates: How They Work and What Affects Your Mortgage Offer
Refinance rates in Texas are the interest rates offered on a new mortgage used to replace an existing home loan. Those rates matter because they affect your monthly payment, your total interest cost, your break-even point, and whether refinancing actually improves your overall loan situation. A lower rate can help, but the lowest advertised rate…
Read More
Can You Refinance a Mortgage With Student Loans?
Refinancing with student loans is often possible, but the student debt can affect whether the new mortgage is approved, how much you can borrow, and how attractive the refinance terms look. For most homeowners, the biggest issue is not simply having student loans. It is how those loans affect debt-to-income ratio, cash flow, credit profile,…
Read More
Refinance While Self Employed: Requirements, Income Documentation, and How Approval Works
Refinancing while self employed is possible, but approval often depends on how clearly your income can be documented and how stable that income looks on paper. A self-employed borrower may earn enough to afford the loan, yet still face extra scrutiny because mortgage underwriting usually relies on tax returns, business records, and year-over-year income patterns…
Read More
Can You Refinance With 50% Equity? What Lenders Consider
Yes, refinancing with 50% equity is often possible, and in many cases it places a borrower in a stronger position than someone with less equity. Having 50% equity generally means your loan-to-value ratio, often called LTV, is about 50%. That is a low LTV, and lenders usually view lower LTV loans as less risky. This…
Read More
Best Refinance Options With a 600 Credit Score
The best refinance options with a 600 credit score are usually government-backed or flexible conventional alternatives, especially FHA rate-and-term refinances, FHA cash-out refinances if equity is strong enough, VA refinance programs for eligible veterans and service members, and in some cases conventional refinancing through lenders that accept lower scores. A 600 score does not automatically…
Read More