Mortgage Approval With a 47% Debt-to-Income Ratio
A 47% debt-to-income ratio is high, but it does not automatically prevent mortgage approval. In mortgage underwriting, a 47% DTI means 47% of your gross monthly income goes toward monthly debt obligations, including the proposed housing payment. Some loan programs may allow that level, while others may be stricter or may require stronger compensating factors…
Read More
What Is PMI? Private Mortgage Insurance Explained
Private mortgage insurance, often shortened to PMI, is a cost many home buyers run into when they make a smaller down payment on a conventional mortgage. It is easy to confuse PMI with property insurance or with mortgage insurance used on government-backed loans, but PMI serves a different purpose. It is designed to protect the…
Read More
FHA Loan With Low Income: Qualification Requirements and Approval Factors
An FHA loan can be one of the more accessible mortgage options for borrowers with modest earnings, but low income by itself does not automatically qualify or disqualify someone. FHA loans are insured by the Federal Housing Administration and are often used by first-time homebuyers because they allow lower down payments and more flexible credit…
Read More
Mortgage Down Payment Requirements With a 680 Credit Score
A 680 credit score is often viewed as a solid mortgage score, but it does not create one fixed down payment requirement. With a 680 score, some borrowers may qualify for low-down-payment options such as 3 percent, 3.5 percent, or 5 percent down, while others may choose or need a larger amount based on the…
Read More
Can You Refinance a Mortgage With Student Loans?
Refinancing with student loans is often possible, but the student debt can affect whether the new mortgage is approved, how much you can borrow, and how attractive the refinance terms look. For most homeowners, the biggest issue is not simply having student loans. It is how those loans affect debt-to-income ratio, cash flow, credit profile,…
Read More
Can I Buy a House With Student Loan Debt?
Yes, you can buy a house with student loan debt. In many cases, student loans are a normal part of the mortgage approval process, and lenders focus on how that debt fits into your overall financial picture rather than treating it as an automatic barrier. Income, credit score, monthly debt payments, savings, and the loan…
Read More
USDA Loan for Multi-Family Homes: Eligibility, Occupancy, and Property Rules
A USDA loan can sometimes be used to buy a multi-family home, but only in a limited way. In most cases, the property must be in an eligible rural area, the borrower must meet income and occupancy rules, and the home usually needs to be owner-occupied. That means a borrower may be able to finance…
Read More
USDA Loan With a 630 Credit Score: Requirements, Approval Factors, and Eligibility
A USDA loan with a 630 credit score may be possible, and for many borrowers it falls into a range where approval can be more achievable than with lower scores. A 630 score is not a guarantee of approval, but it can meet the credit expectations used by many lenders for USDA-backed home loans. Income,…
Read More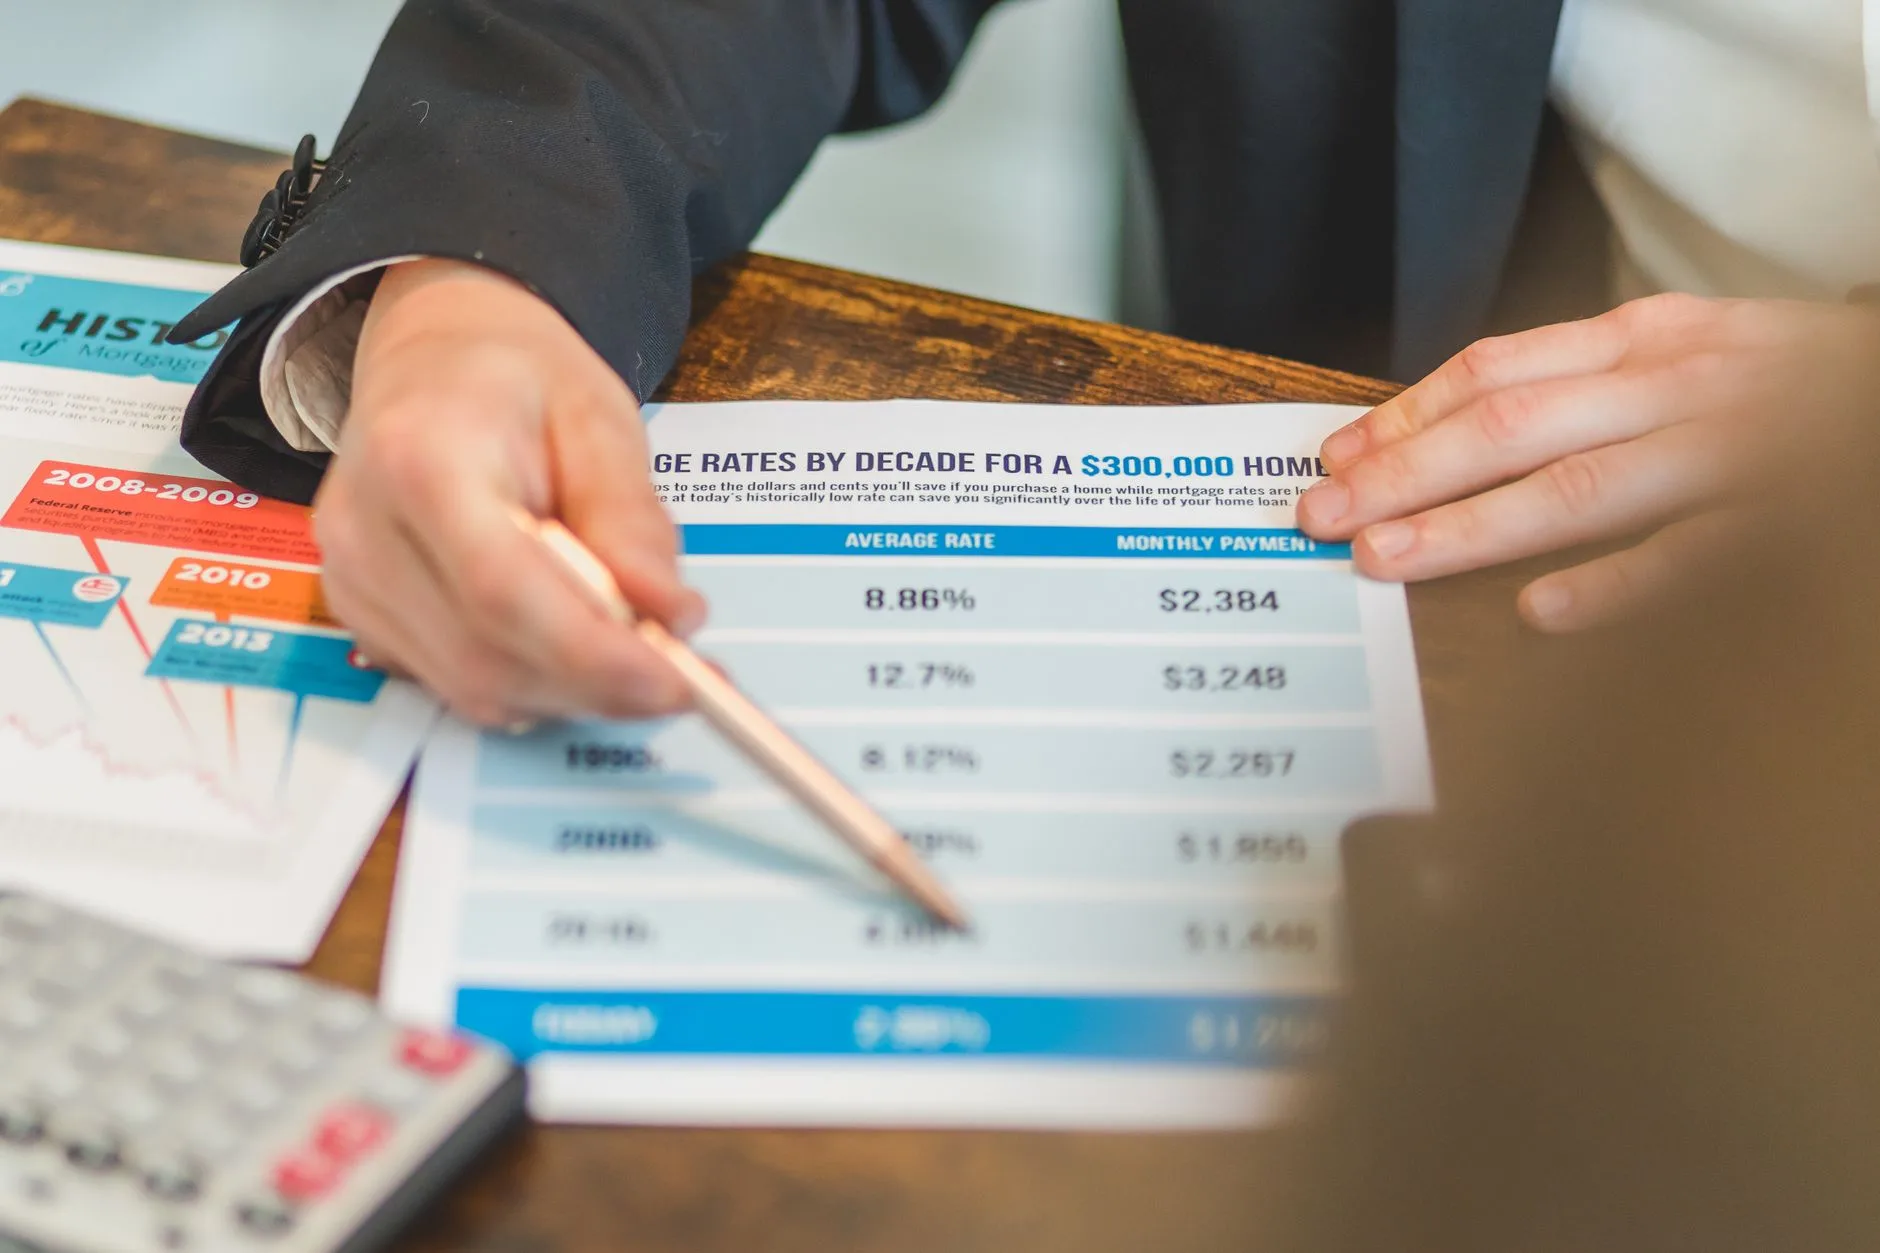
How Interest Rate Affects a Mortgage: Monthly Payments and Total Loan Cost
Interest rate is one of the most important numbers in a mortgage because it directly affects how much the loan costs over time. Even a small difference in rate can change the monthly payment and the total amount paid over the life of the loan. For many borrowers, the interest rate is the first figure…
Read More
FHA Loan Approval Process: Steps, Requirements, and What Lenders Review
The FHA loan approval process is the step-by-step review a lender uses to determine whether a borrower and property meet Federal Housing Administration guidelines. FHA loans are government-backed mortgages insured by the FHA, and they are commonly used by first-time homebuyers and borrowers who need a lower down payment or more flexible credit standards than…
Read More