Author: Kevin
Mortgage Approval With 31% Debt-to-Income Ratio Explained
A 31% debt-to-income ratio is generally considered strong in mortgage underwriting. In many cases, that level of monthly debt may leave enough room for a lender to see the borrower as manageable from a repayment standpoint, especially if income is stable and the rest of the file is clean. Debt-to-income ratio, often called DTI, compares…
Read More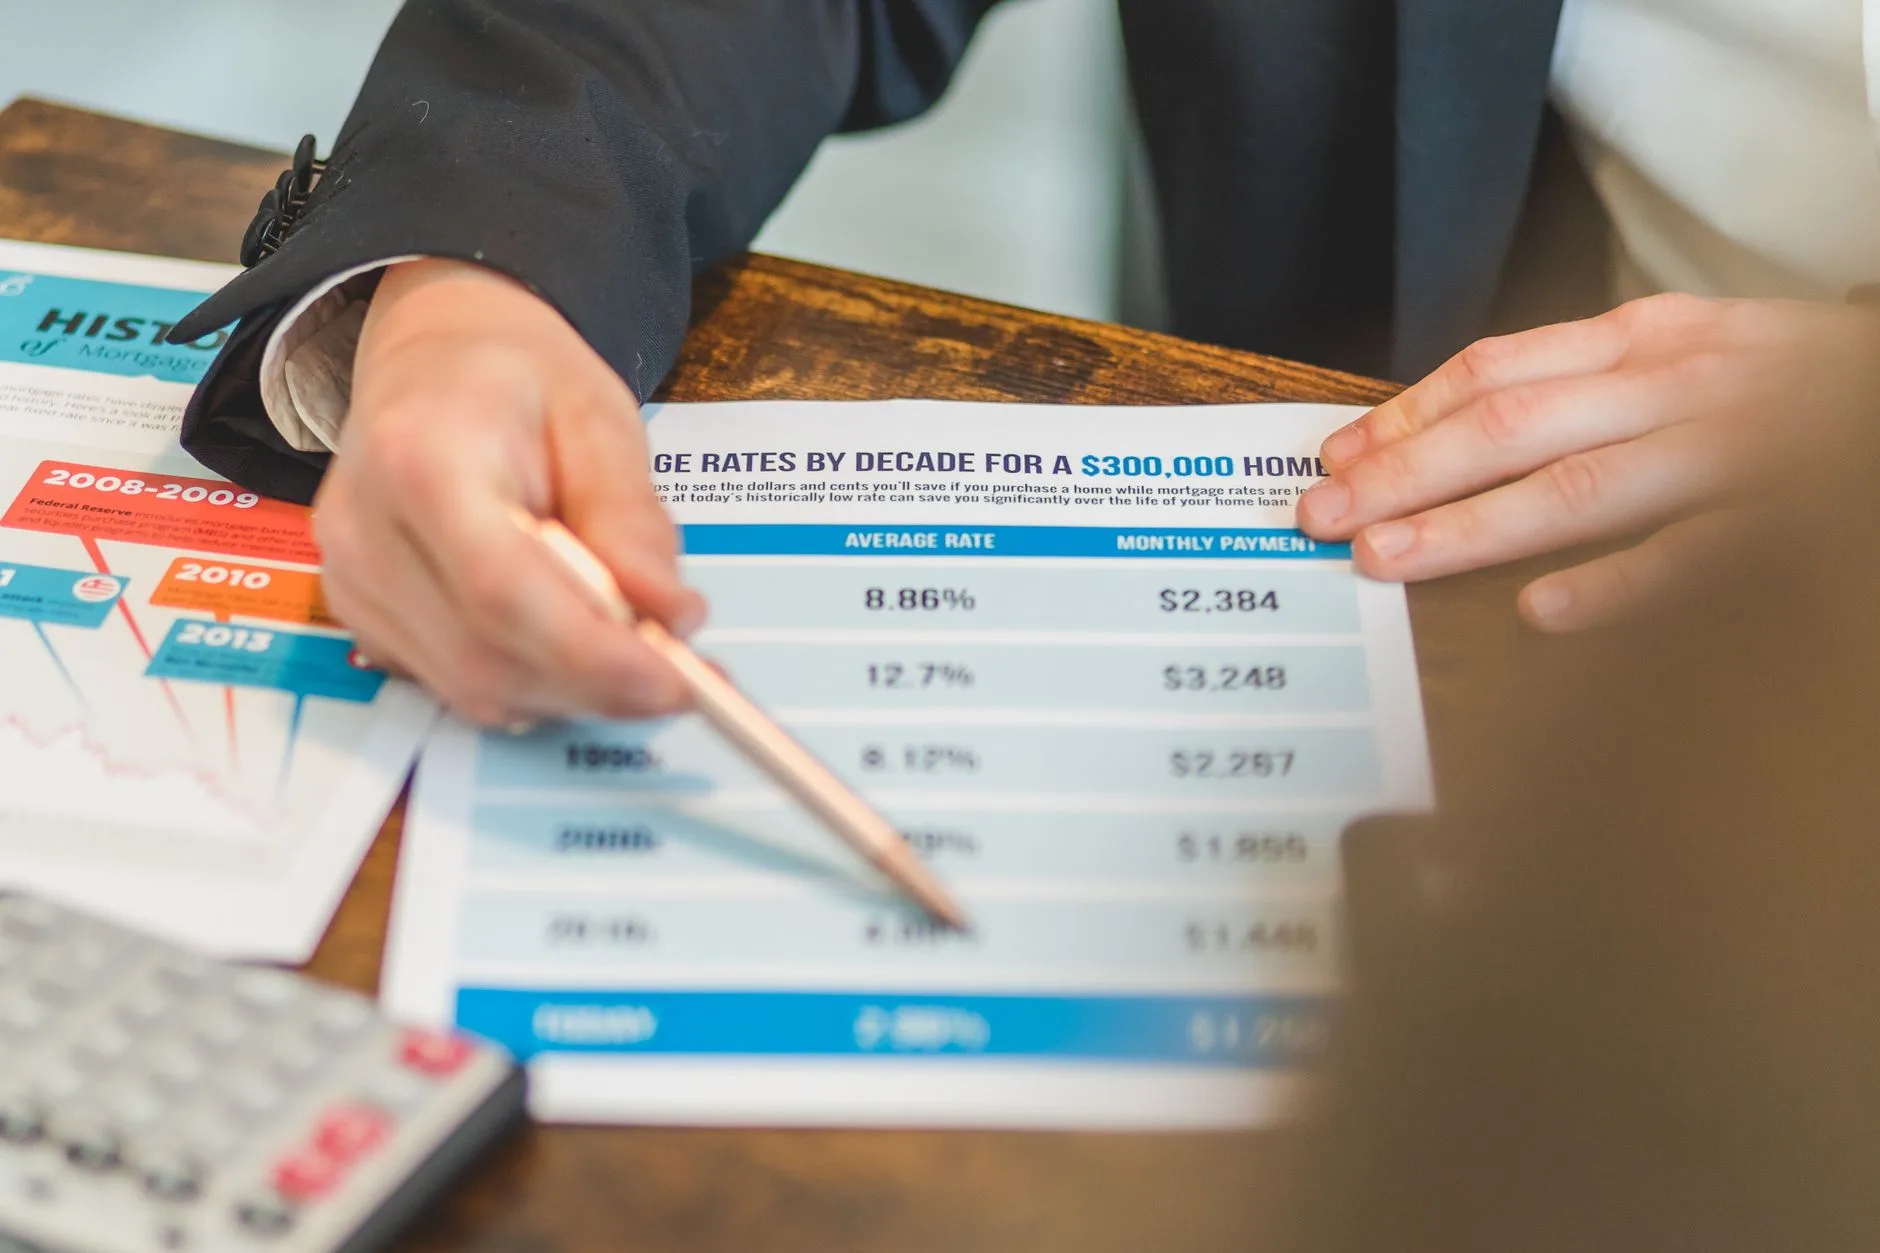
How Does Refinancing Work? What a Mortgage Refinance Changes
Refinancing works by replacing your current mortgage with a new home loan. The new loan pays off the old one, and from that point forward you make payments on the refinance loan instead of the original mortgage. Homeowners refinance for different reasons, including lowering the interest rate, changing the loan term, switching from an adjustable-rate…
Read More
Condo vs House: Key Differences in Cost, Maintenance, and Ownership
Choosing between a condo and a house is often less about which option is universally better and more about which one fits your budget, lifestyle, maintenance preferences, and long-term plans. A condo can offer a lower-maintenance path to homeownership, while a house may provide more privacy, control, and flexibility. Mortgage approval, monthly costs, and even…
Read More
FHA Loan Requirements: Credit Score, Down Payment, DTI, and Property Standards
FHA loan requirements are the rules borrowers and properties generally need to meet in order to use an FHA-insured mortgage. These loans are backed by the Federal Housing Administration and are often used by first-time homebuyers because they can allow lower down payments and more flexible credit standards than many conventional loans. At the same…
Read More
Common Mortgage Qualification Requirements Mistakes to Avoid
Common mortgage qualification requirements mistakes usually happen when borrowers focus on one part of approval, such as credit score, and overlook the other pieces lenders review. Mortgage qualification is based on a combination of credit, income, debt, assets, employment history, and documentation. A borrower can meet one requirement and still run into problems if another…
Read More
What Is a Jumbo Loan? Definition, Requirements, and How It Works
A jumbo loan is a mortgage that exceeds the conforming loan limit set for a particular county. Because the loan amount is larger than what can be sold to Fannie Mae or Freddie Mac as a standard conforming loan, jumbo loans often follow different approval guidelines. They are commonly used for higher-priced homes or for…
Read More
What Is an FHA Loan? How It Works, Requirements, and Pros and Cons
An FHA loan is a government-backed mortgage insured by the Federal Housing Administration. It is commonly used by first-time homebuyers and other borrowers who may need a lower down payment or more flexible credit standards than many conventional loans offer. FHA financing can make homeownership more accessible, but it also comes with important tradeoffs, especially…
Read More
Can I Get a Mortgage With a 550 Credit Score?
A mortgage with a 550 credit score may be possible, but it is usually more difficult and often more limited than borrowing with higher credit. Lenders look at more than the score itself, including income, debt, savings, employment history, down payment, and the type of loan program. A 550 score can signal past credit problems,…
Read More
Georgia Down Payment Assistance Programs: How They Work and Who Qualifies
Georgia down payment assistance programs can help eligible home buyers reduce the upfront cash needed to purchase a home. These programs are commonly used by first-time buyers, but some are also available to repeat buyers, depending on the program rules. Assistance may come in the form of a deferred loan, a forgivable second mortgage, or…
Read More
Mortgage Qualification Requirements Explained: Credit, Income, Debt, and Down Payment
Mortgage qualification requirements are the standards lenders use to decide whether a borrower is likely to repay a home loan on time. These requirements usually include credit score, income, employment history, debt-to-income ratio, down payment, assets, and documentation. Each part helps a lender measure risk and determine which loan programs may fit a borrower’s situation.…
Read More